XALPHA: A Memory-Driven AI Quant Researcher for Hypothesis-to-Code Alpha Discovery
arXiv preprint arXiv:2607.08332, 2026
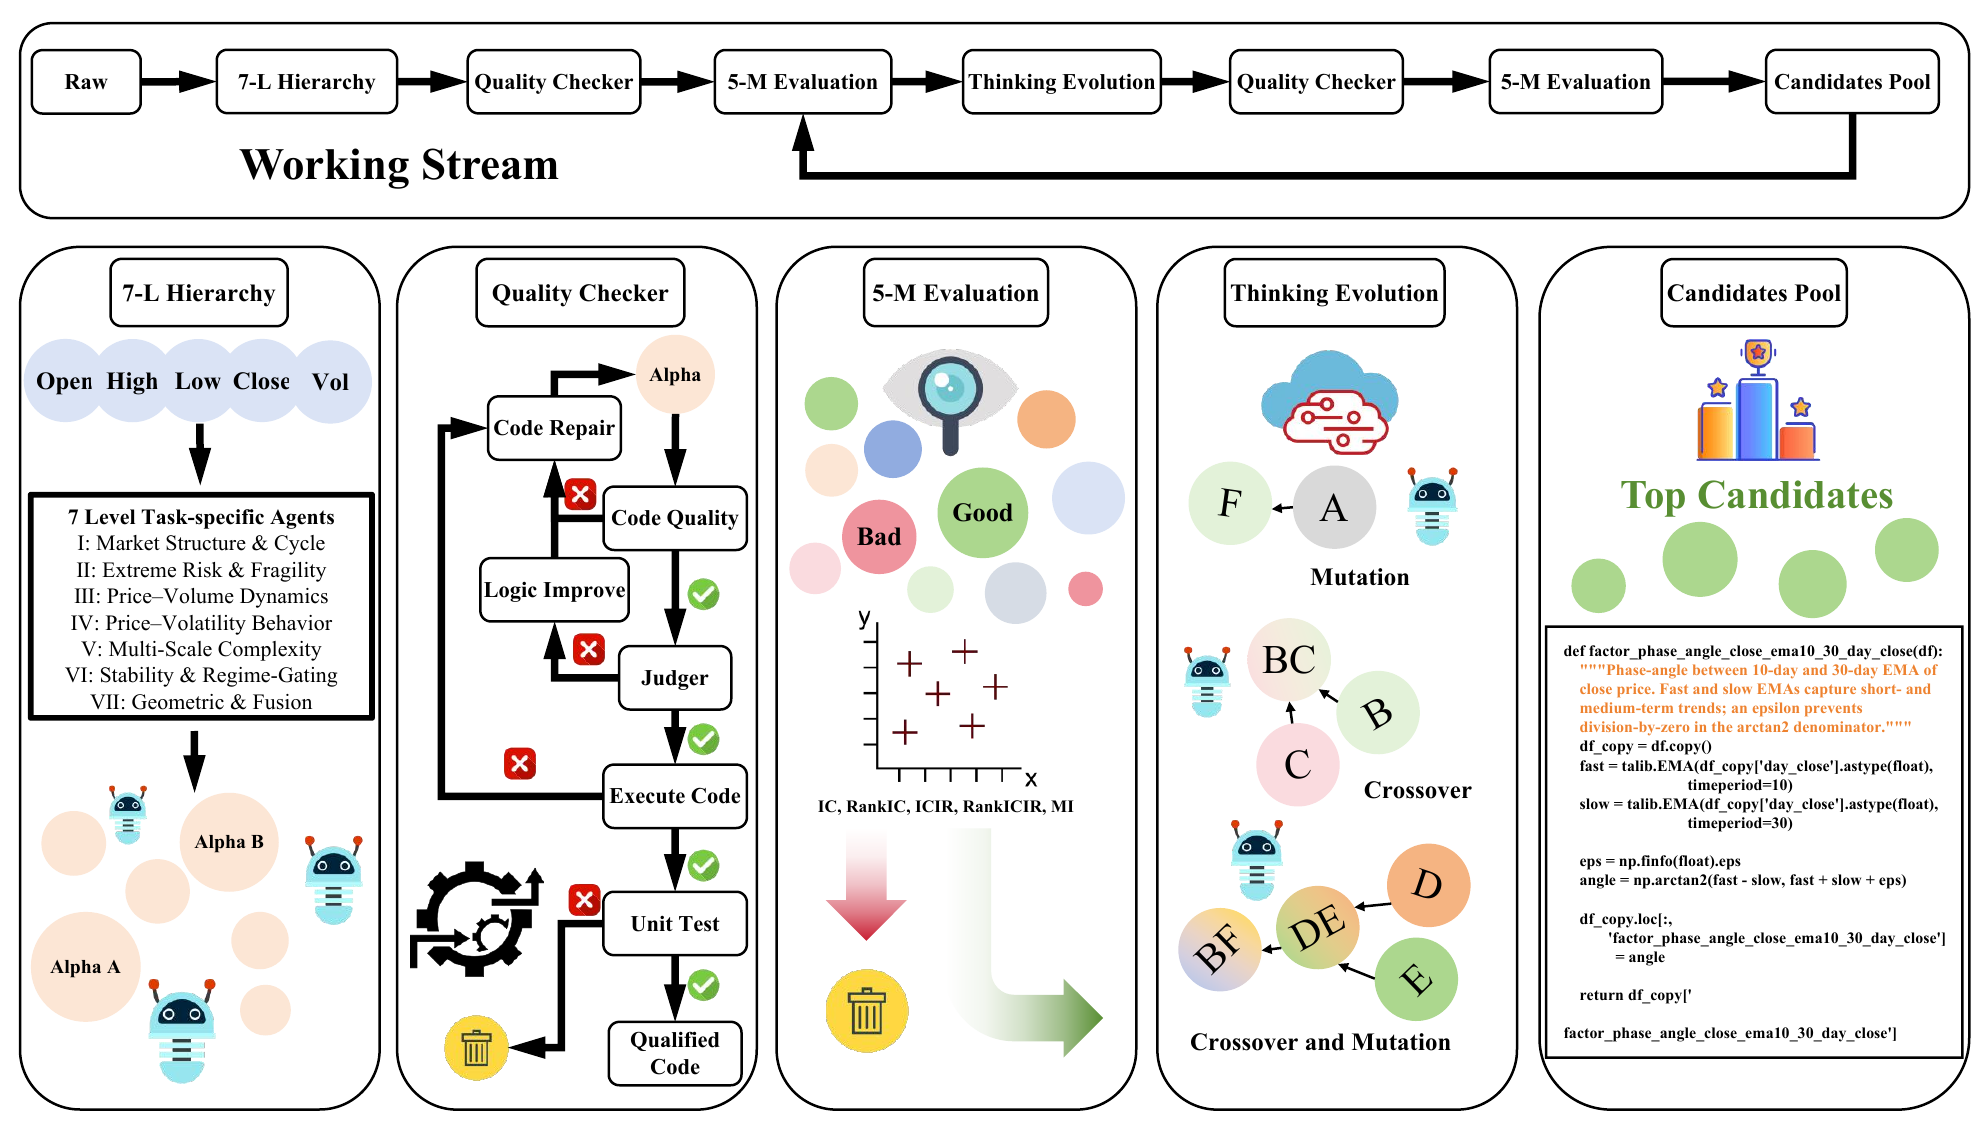
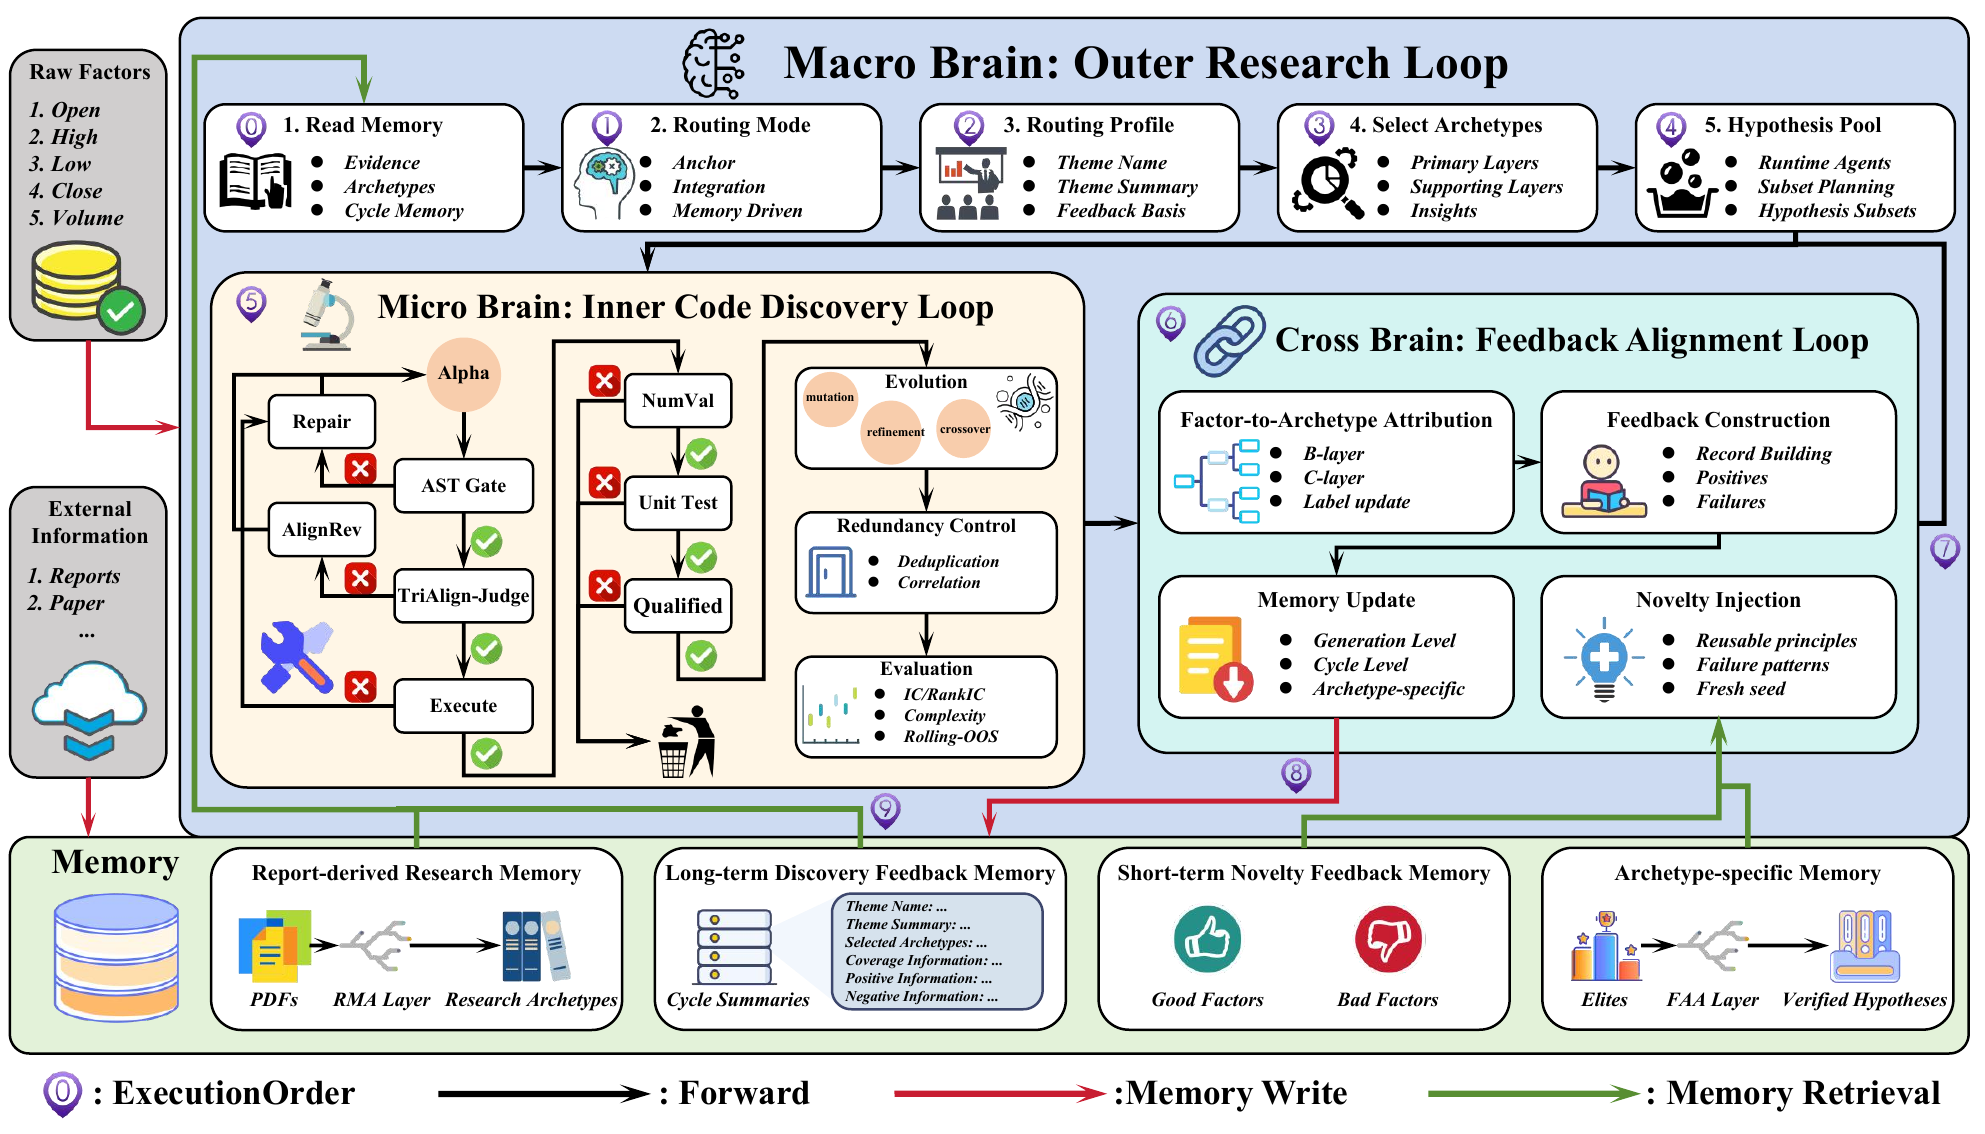
Financial markets are noisy, non-stationary, and high-dimensional, making it difficult to discover predictive and robust trading signals. Alpha discovery has evolved from manual factor design to machine learning, evolutionary search, and recent LLM-based frameworks, improving the efficiency of factor generation, search, and evaluation.